The Credit Line a Cane Corso Owner Should Arrange
Bringing a magnificent Cane Corso into your life is a profound joy, but it also comes with a weighty responsibility – especially when it comes to their health. While we lovingly budget for their premium food and essential training, the reality is that unexpected, high-cost veterinary emergencies or chronic health conditions can strike at any time, leaving many owners feeling overwhelmed and financially unprepared. This guide is here to walk you through the proactive steps of arranging a credit line, a vital financial safety net, so you can make health decisions for your beloved giant based on what's best for them, not just what you can afford in a crisis.
The Unpredictable Reality of Cane Corso Expenses
Let's be real: owning a Cane Corso isn't just about the initial purchase price; it's a marathon of ongoing costs, and some of the biggest ones are entirely unpredictable. These are large, powerful dogs, and with their size comes a predisposition to certain health issues that can carry hefty price tags. Thinking ahead about how to handle these potential financial blows is not being pessimistic; it's being a responsible, loving owner.
Major Health Concerns and Their Costs
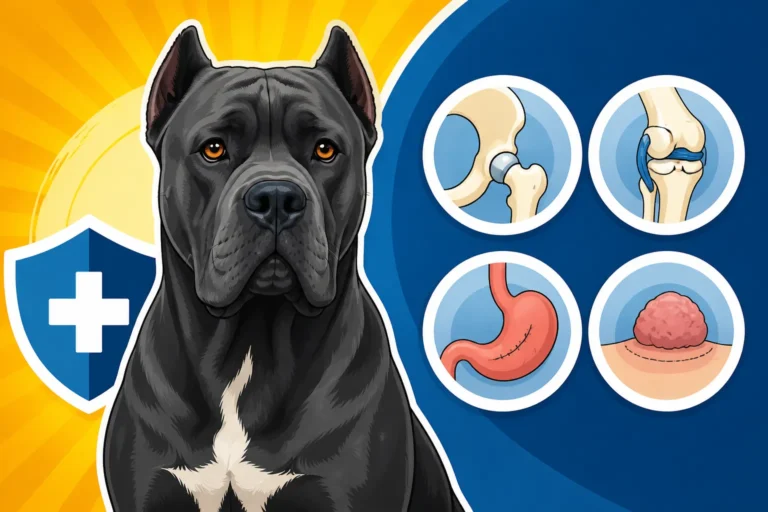
When you commit to a Cane Corso, you're not just getting a loyal companion; you're also taking on the potential for some significant veterinary bills down the line. Conditions like hip and elbow dysplasia are unfortunately common in large breeds, and while good breeding practices aim to reduce the risk, they don't eliminate it entirely. Imagine your sweet, clumsy puppy suddenly limping, and an x-ray reveals that a hip replacement could be on the horizon. The costs for such orthopedic surgeries can be staggering, easily reaching into the thousands. Hip Surgery Costs on a Hundred Pound Cane Corso can be a real shock if you haven't prepared.
Then there's the ever-present threat of bloat, or Gastric Dilatation-Volvulus (GDV), a life-threatening condition where a deep-chested breed's stomach twists. This is a terrifying emergency that requires immediate surgical intervention, and the hours that decide a bloat outcome are critical. What It Costs When a Cane Corso's Stomach Turns often involves emergency vet visits, complex surgery, and potentially several days of hospitalization. Without a rapid response and the funds to cover it, the outcome can be tragic. Even routine anesthesia for something like a dental cleaning or a spay/neuter comes with higher Anesthesia Charges on a Hundred Pound Cane Corso due to their size and the increased monitoring required.
Chronic Conditions That Add Up
It's not always about a single, massive emergency. Sometimes, it's the ongoing management of a chronic condition that slowly drains your savings. Epilepsy, for instance, can manifest in Cane Corsos, often around the age of two or three. Why a Cane Corso's Epilepsy Surfaces at Two or Three means a lifetime of daily medication and regular vet check-ups. The initial diagnostic workup, which can include extensive blood tests and even an MRI, is already a significant expense. The Bill for a Cane Corso's Seizure Workup can be substantial. Beyond that, the monthly cost of anticonvulsant medications, even generic ones, can truly add up over years, creating a continuous financial burden that many don't foresee.
Skin allergies, thyroid issues, or even simple recurring ear infections can also lead to chronic care needs, involving specialized diets, expensive medications, and frequent vet visits. These aren't necessarily life-threatening emergencies, but they chip away at your budget, demonstrating why having access to funds beyond your immediate cash flow is so important.
Exploring Your Credit Line Options for Pet Care
When faced with these potential financial realities, simply hoping for the best isn't a strategy. Having a pre-arranged credit line can provide immense peace of mind. It’s not about encouraging irresponsible spending, but about having a safety net for the health and well-being of your Cane Corso.
Pet-Specific Credit Options
One popular route many pet owners take is applying for a dedicated pet healthcare credit card. These are specifically designed for veterinary expenses and often come with promotional offers like interest-free periods if the balance is paid within a certain timeframe. The application process is similar to a standard credit card, involving a credit check, and if approved, you get a line of credit specifically for vet bills.
The main advantage here is that these cards are accepted at many veterinary clinics, making the payment process seamless during a stressful situation. The interest-free periods can be a lifesaver, giving you several months to pay off a large bill without incurring additional charges. However, if you don't pay off the balance in full before the promotional period ends, the interest rates can be quite high, sometimes retroactively applied to the original purchase date. It's crucial to understand these terms fully before committing.
Personal Loans and General Credit Cards
Another option is a personal loan, either from your bank or an online lender. Personal loans typically offer lower, fixed interest rates compared to general credit cards, and you'll have a set repayment schedule, which can be easier to manage for large, one-time expenses like a major surgery. The downside is that they require a formal application and approval process, which might take a few days, making them less ideal for immediate emergencies unless you've pre-qualified.
Standard credit cards are the most accessible option, as many people already have one. They offer immediate access to funds, which is excellent for true emergencies. However, their interest rates can be higher, and it's easy to let a large balance accumulate if you're not diligent with payments. For routine expenses, like buying a new type of large breed food or supplements from retailers like Chewy, or specialty meals from Ollie, using a regular credit card might be fine, but for a sudden four-figure vet bill, the interest can become a real burden quickly.
| Financial Tool | Pros | Cons | Best For |
|---|---|---|---|
| Pet-Specific Credit | Promotional interest-free periods, widely accepted at vet offices | High interest rates after promo, only for pet care | Planned large vet bills, emergencies |
| Personal Loan | Lower fixed interest rates, predictable payments | Slower approval, not ideal for immediate emergencies | Large, known expenses (e.g., scheduled surgery) |
| General Credit Card | Immediate access to funds, flexible use | Potentially very high interest rates, easy to accumulate debt | Emergencies, smaller routine expenses |
| Pet Insurance | Covers a percentage of eligible vet bills, budget predictability | Monthly premiums, deductibles, reimbursement model, pre-existing exclusions | Long-term protection against unexpected illness/injury |
| Dedicated Savings | No interest owed, complete control over funds | Takes time to build, may not be enough for catastrophic events | Routine care, smaller unexpected expenses |
Responsible Management: Using Your Credit Line Wisely
Having a credit line available is a powerful tool, but like any powerful tool, it needs to be wielded with care and responsibility. The goal is to provide your Cane Corso with the best care, not to put yourself into unmanageable debt.
Proactive Setup and Understanding Terms
The best time to arrange a credit line is before you need it. Don't wait until your Cane Corso is in crisis and you're making rushed decisions under emotional duress. Research your options when your dog is healthy. Compare interest rates, annual fees, and repayment terms across different providers. If considering a pet-specific credit card, understand exactly how the promotional interest-free periods work and what the interest rate jumps to if you don't pay it off in time. Make sure you know if certain procedures, like The Cost of Cropping a Cane Corso's Ears or other non-medical procedures, are covered if that is something you consider.
For a general credit card or personal loan, read all the fine print. How long is the repayment period? Are there any hidden fees? A pre-approved credit line that you simply hold onto for emergencies is a smart move. It means you’ve already done the homework and the funds are accessible when needed, without the added stress of applying mid-crisis.
Budgeting for Repayment and Avoiding Debt Traps
Once you use a credit line, immediate and disciplined repayment must become a priority. Think of it as an interest-free loan that you are working hard to pay back before those interest charges kick in. Create a clear budget for how you will repay the balance. Can you make larger payments than the minimum required? Can you temporarily cut back on other discretionary spending to accelerate repayment?
It’s easy to fall into the trap of only making minimum payments, which can drag out the repayment period and significantly increase the total amount you pay due to accumulating interest. For your Cane Corso's sake, and your own financial health, aim to pay off any balance incurred for their care as quickly as possible. This means viewing the credit line as a bridge, not a permanent solution for ongoing costs. For everyday needs, such as ensuring your Cane Corso has Chews That Survive a Cane Corso's Jaw, consider budgeting for these items from your regular income rather than relying on a credit line.
Beyond Credit: A Holistic Financial Plan for Your Cane Corso
While a credit line is an excellent safety net, it's just one piece of a comprehensive financial plan for your Cane Corso. The most robust approach combines several strategies to ensure you're ready for anything.
The Role of Pet Insurance
Many Cane Corso owners find pet insurance to be an invaluable component of their financial strategy. Companies like Healthy Paws offer various plans that can cover a significant portion of eligible veterinary bills, from accidents and illnesses to surgeries and chronic conditions. Monthly Pet Insurance Premiums on a Cane Corso can vary depending on your dog's age, breed, and your chosen coverage level, but they provide predictable monthly expenses instead of sudden, crushing blows.
However, pet insurance usually works on a reimbursement model, meaning you pay the vet upfront and then submit a claim for repayment. This is where a credit line can perfectly complement insurance: you use your credit line to cover the initial vet bill, and then use the insurance reimbursement to pay down your credit card balance. It's a powerful combination for large, unexpected costs. Be mindful that Whether a Cane Corso's Epilepsy Counts as Pre-Existing or other conditions diagnosed before coverage begins are often excluded.
Building an Emergency Savings Fund
Perhaps the most ideal scenario is to have a dedicated emergency savings fund specifically for your Cane Corso. This is money that you set aside regularly, little by little, specifically for unexpected vet bills. Unlike a credit line, savings don't accrue interest; instead, they earn interest, no matter how small. Whether a Cane Corso Owner Should Self Insure Instead is a common question, and for some, building a robust savings account is their preferred method.
The challenge, of course, is building this fund. It takes discipline and time. Start small, even if it's just putting away a few dollars each week. Over time, that money grows, offering a buffer against life's curveballs. If you manage to build a substantial fund, you might find that you rarely need to tap into your credit line, or only for truly catastrophic events that exceed your savings.
Ultimately, a Cane Corso is more than a pet; they're family. Providing them with the best possible care means being prepared for all eventualities. Whether it's a pre-arranged credit line, robust pet insurance, a dedicated savings fund, or ideally, a combination of all three, taking these steps ensures you're ready to face whatever comes your way, giving your loyal companion the long, healthy life they deserve. Thinking about What Ten Years With a Cane Corso Adds Up To helps put these financial preparations into perspective.
Disclaimer
This article is for general informational purposes only and does not constitute professional advice. Laws, prices and regulations vary by location and change over time. Consult a qualified professional for guidance on your specific situation.